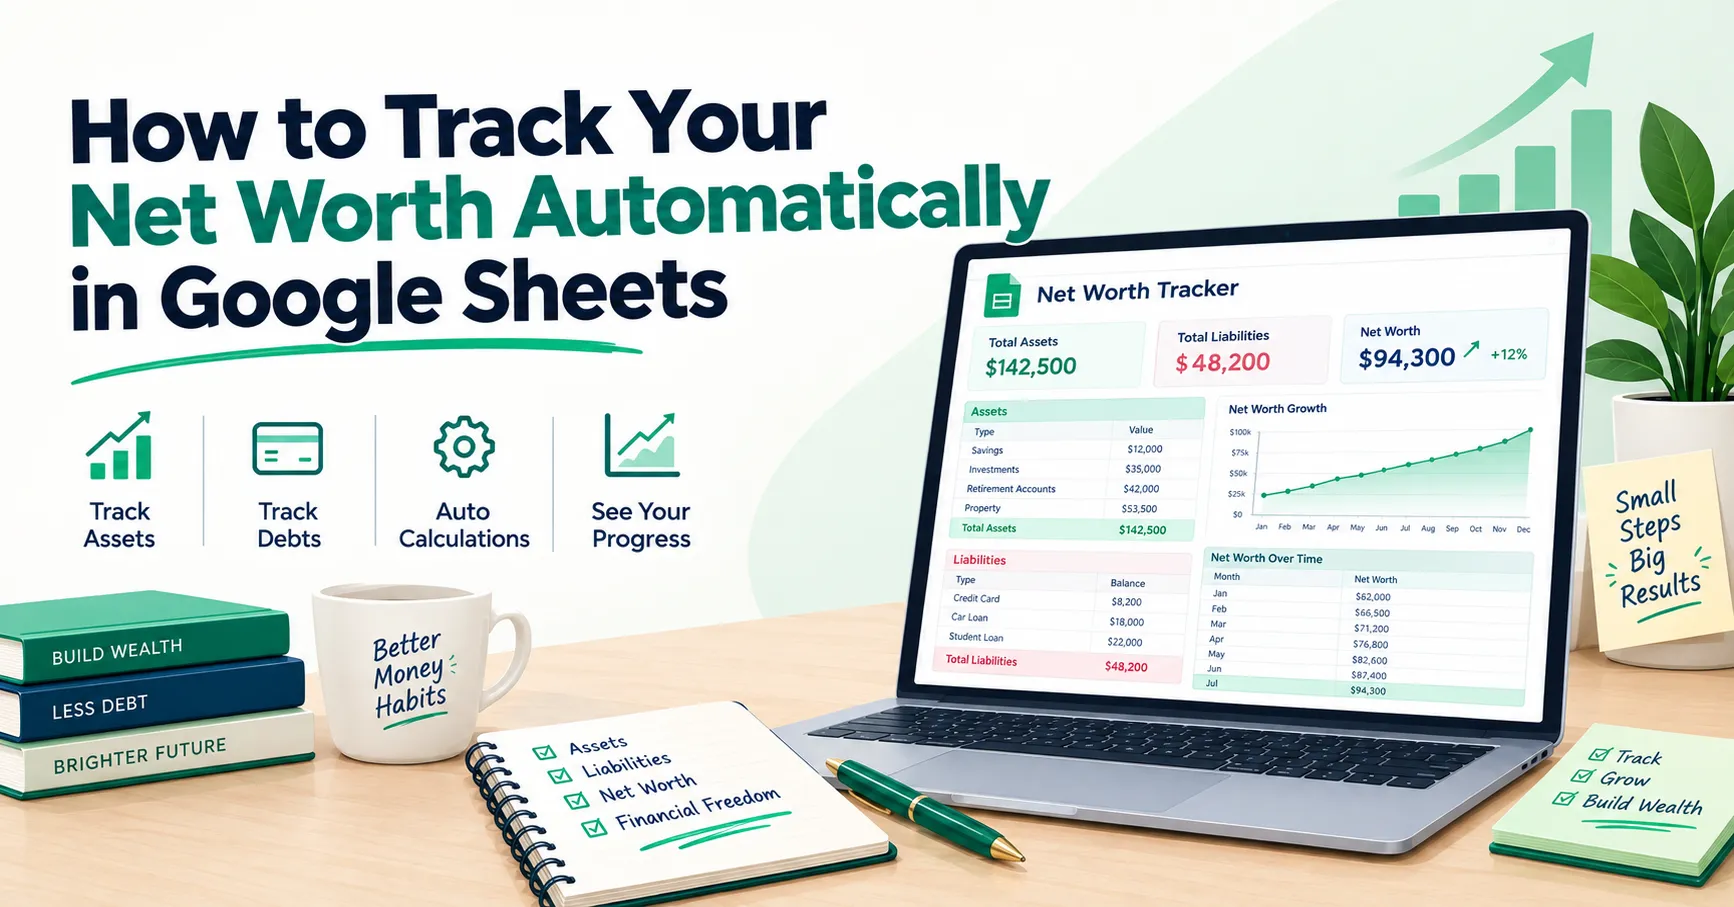
Your net worth is one number that tells you a lot: what you own minus what you owe. This calculator lets you list out your assets and liabilities individually, see your total net worth, and track how it’s changed since the last time you checked.
Net Worth Calculator
Add up what you own and what you owe to see where you stand.
Assets (what you own)
Liabilities (what you owe)
From last time you tracked it, to see your change.
Assets vs. Liabilities
What Is a Net Worth Calculator?
A net worth calculator adds up everything you own (your assets) and everything you owe (your liabilities), then subtracts the second number from the first to give you your net worth.
The basic idea is simple, but seeing it broken down by individual item, cash, retirement accounts, a car, credit card debt, a car loan, gives you a much clearer picture than just a single total. It also makes it easier to see which liabilities are weighing your number down the most.
If you’ve checked your net worth before, this calculator can also show you how much it’s changed since then, which is often more motivating to track than the raw number alone.
How to Use This Calculator
- List your assets. Add each item you own with real value, like cash and savings, retirement accounts, property, or vehicles, along with its current value. Use “Add asset” for more than the two starting rows.
- List your liabilities. Add each debt you owe, like credit card balances, loans, or a mortgage, along with the amount owed. Use “Add liability” for more than the two starting rows.
- Optional: enter your previous net worth. Under advanced options, enter your net worth from the last time you calculated it to see how much it has changed.
- Click “Calculate Net Worth.”
- Review your results. You’ll see your total assets, total liabilities, and overall net worth, along with the change since your last calculation if you entered one. A chart compares your assets and liabilities visually, and a table breaks down each item.
These numbers reflect the values you enter, so they’re only as accurate as your most current account balances and estimated asset values.
Why This Matters
Net worth is one of the clearest ways to track overall financial progress over time, since it accounts for both what you’re building up and what you still owe. Someone with a high income but heavy debt can have a lower net worth than someone with a modest income and few liabilities.
Checking this number regularly, monthly or quarterly for most people, helps you see the bigger picture beyond day-to-day spending decisions. Paying down a credit card and growing a retirement account both move this number in the same direction, even though they can feel like unrelated goals day to day.
It’s worth remembering that a single net worth snapshot doesn’t capture everything about your financial health, like your income stability or emergency savings. It’s one useful data point among several, not the whole story.
Tips to Get the Most Out of Your Net Worth Tracking
Check it on a consistent schedule. Monthly or quarterly works well for most people. Checking too often can make normal market or balance fluctuations feel more significant than they are.
Use realistic asset values. For things like a home or car, use a reasonable current estimate rather than the original purchase price, since values change over time.
Track your previous net worth each time. Entering your last calculated number lets you see the change over time, which is often more useful for motivation than the total figure alone.
Common Mistakes to Avoid
Forgetting smaller liabilities. A small personal loan or a “buy now, pay later” balance can be easy to overlook but still counts against your total. Include every debt, even small ones.
Overestimating asset values. It’s tempting to inflate the value of a car or home, but using an optimistic number will give you an inflated net worth that doesn’t reflect reality if you had to sell.
Comparing your net worth to others without context. Everyone’s timeline, income, and starting point are different. Comparing your number to a friend’s or a number you saw online rarely gives useful insight, since it ignores the full context behind it.
Frequently Asked Questions
What counts as an asset?
Anything you own that has real monetary value: cash and savings, retirement or investment accounts, property, and vehicles are common examples. Personal belongings without significant resale value are usually left out.
What counts as a liability?
Any debt you owe, including credit card balances, car loans, student loans, personal loans, and mortgages.
Is a negative net worth bad?
A negative net worth simply means your liabilities currently exceed your assets, which is common, especially early in adulthood or after taking on a mortgage or student loans. What matters more is the direction it’s moving over time.
How often should I calculate my net worth?
Monthly or quarterly is a common approach for most people. It’s frequent enough to see meaningful trends without overreacting to short-term fluctuations.
Should I include my home’s full value or just my equity?
This calculator asks for asset value and liability amount separately, so list your home’s full estimated value as an asset and your remaining mortgage balance as a liability. The calculator will net them out correctly in your total.
Track the Trend, Not Just the Number
Your net worth will move up and down as life happens, and that’s completely normal. What matters most is the overall direction over months and years, not any single snapshot.
If a chunk of your liabilities is credit card or loan debt, download the free SheetsWell Debt Payoff Tracker to work it down, and join the SheetsWell email list for more tools to help you track your progress.